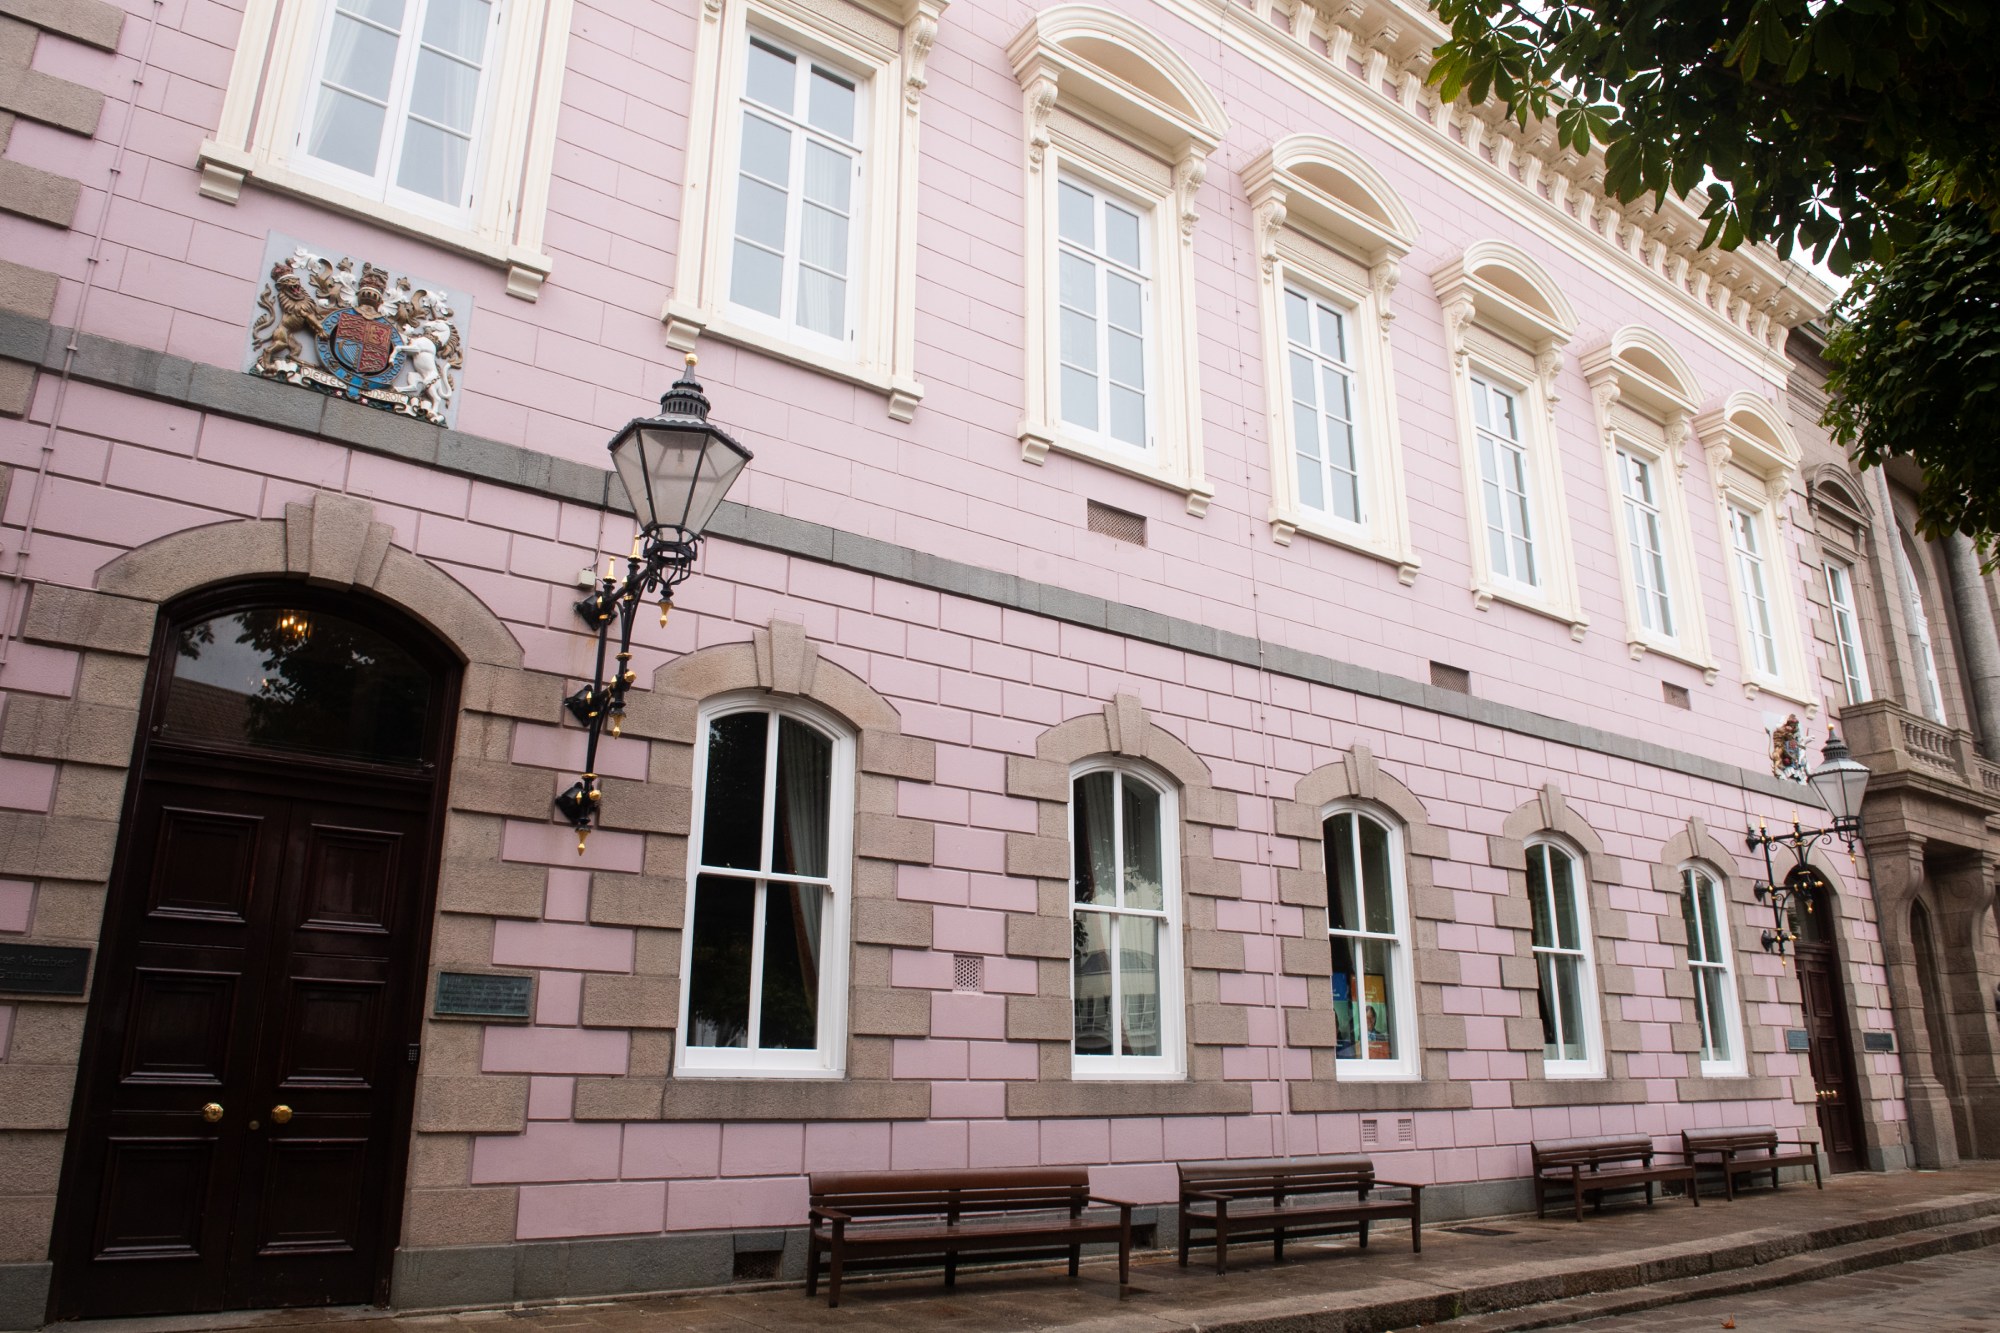

Jersey’s Royal Court has unwound a £17.3 million trust after incorrect advice left a retired banking professional facing millions in unexpected tax bills.
The 70-year-old woman established the Jersey-based Puffin Trust in April 2018, believing it would provide long-term tax protection and help pass wealth to her family.
But her adviser had miscalculated when she would become treated as UK-domiciled for tax purposes, overlooking years she had previously spent living in Britain.
Declaring the trust invalid, the court said: “The advice she received was simply wrong.”
The woman, who is anonymised in the judgment, and her husband had both worked in banking. They moved to London in 1983, lived abroad between September 2000 and September 2005, and are now retired in England.
She relied on Stephen Green, a partner at law firm Wiggin Osborne Fullerlove, for advice about her domicile status.
Mr Green told her that she would not become deemed UK-domiciled until April 2020 and could establish an offshore trust before then to benefit from her existing tax status.
Relying on that advice, she transferred cash and other assets worth approximately £17.3 million into the trust. Her wishes were for the funds principally to benefit her two daughters and, subsequently, her grandchildren.
However, in December 2025, Mr Green discovered a problem while preparing inheritance-tax filings.
The woman had actually become deemed UK-domiciled in April 2017, before the trust was established.
The court found that Mr Green had failed to account for her UK residence before 2000, despite being aware of it and having a comprehensive note of her history.
The resulting liabilities included an initial inheritance-tax charge of approximately £4.245 million, interest of £1.63 million by July 2026, and potential penalties.
There were also further inheritance-tax consequences and significant income-tax and capital-gains-tax charges amounting to £2.2 million, plus possible interest and penalties.
The woman told the court: “These consequences were not merely unexpected but wholly inconsistent with the advice I had received and the careful and entirely standard planning I believed I was implementing when I established the Trust.”
The court found that she would not have entered into the arrangement but for the mistake.
“This was not an aggressive tax mitigation strategy but rather a straightforward plan to take advantage of her supposed domicile,” the judgment said.
The Bailiff, Sir Robert MacRae, sitting with Jurats Powell and Le Heuzè, concluded that refusing relief would be “quite unjust”.
The court declared the trust invalid and set aside the transfers, meaning the assets are treated as having always been held directly for the woman.
The judgment says no inheritance tax will now be due, although some adverse income-tax and capital-gains-tax consequences remain.
HMRC said it would adhere to the court’s order. The woman’s family supported the application, and the court confirmed that £16,000 previously distributed to charities could remain with them.