During last week’s GST debate, Policy & Resources (P&R) warned that a lower S&P credit rating could make £250m of future borrowing tens of millions of pounds more expensive.
But if protecting the island’s credit rating and borrowing costs were going to become such a significant part of the debate around GST, why were they not set out in the Tax Policy Letter?
The issue became one of the key flashpoints of last week’s debate, after opponents questioned why the £250m borrowing figure and the potential impact of higher interest costs did not appear at all in the 172-page document deputies were asked to approve.
The criticism echoes a familiar warning from police cautions: ‘it may harm your defence if you do not mention when questioned something which you later rely on in court’.
Some GST opponents argue P&R’s approach created a similar problem – that key arguments and figures were only introduced in the chamber, rather than being set out when they were first asked to consider it.
Responding to Express, Deputy Niles rejected suggestions that P&R was using GST to fund £250m of borrowing, saying the figure related to two existing or planned projects.
“The responsible question is not whether to invest but how to do so at the lowest possible cost,” he added.
The original GST argument
For weeks before the debate, P&R’s central argument for GST focused on Guernsey’s underlying finances.
The committee warned that the island was facing a long-term “black hole” of around £50m a year, with spending pressures expected to outpace recurring income.
P&R argued that without raising more tax money, Guernsey would face difficult decisions in the future, including pressure on public services and further financial measures.
Critics, however, argued that the answer should not simply be raising more tax. They questioned whether P&R should first focus on reducing spending, finding efficiencies and tackling what they described as waste within government.
The S&P row flares up
But during the final debate, a different warning emerged: that failing to introduce GST could damage Guernsey’s S&P credit rating, adding tens of millions of pounds to future borrowing costs.
For the five weeks before the debate, P&R had been publicly making the case for GST – as far as we can tell without talking about S&P or borrowing costs.
The 172-page Tax Policy Letter does not mention S&P at all, and only refers to borrowing four times – including a repeated statement that: “The States cannot borrow their way out of financial difficulty without the surplus required to repay the debt.”
That changed when deputies began debating the proposals.
Deputy Andrew Niles told the Assembly that S&P was “a very important aspect” of Guernsey being “a credible government that has the ability to be able to raise money”.
He said: “If we don’t have that rating, if we have an alternative rating that is lower, it costs us money. It not only costs us money tomorrow; it costs us money forever.”
Deputy Lindsay de Sausmarez also warned that a downgrade could add “many tens of millions of pounds” to borrowing costs over a 40-year period.
The criticism from opponents was not that P&R had never considered S&P, but that it waited until the States Assembly meeting to present to deputies.
WhatsApp group
The S&P argument sparked a fresh row, as opponents suggested the link between credit ratings and borrowing had already been discussed privately before it reached the Assembly floor.
Deputy Garry Collins challenged Deputy Niles over comments he had made in a deputies’ WhatsApp group, appearing to suggest the issue had been raised before the debate.
Deputy Gavin St Pier said that as the policy letter didn’t mention credit ratings or borrowing it was “deeply unhelpful” of P&R to “pluck numbers such as £250 million out of the air… I think it undermines the case”.
Deputy Andy Sloane said Deputy Niles had “rather refreshingly admitted” on WhatsApp that “getting good S&P ratings is all about being able to borrow more” – a claim Deputy Niles didn’t dispute in the Chamber.
The exchange added to pressure on P&R over whether the S&P and borrowing argument had been fully set out before deputies were asked to vote.
P&R pushes back
Deputy Niles said the £250m figure referred to two projects already in the public domain: £150m for affordable housing and £100m to pay for a second undersea cable for Guernsey Electricity.
He said the housing borrowing had already been agreed by the States and would be repaid through rental income from the homes built, “not through general taxation”.
He said any borrowing for the undersea cable would be paid for through electricity bills “in the normal way, just as the debt for the existing cable has been”.
Deputy Niles said raising the figure in the Assembly was not about suggesting GST would fund those projects, but about explaining why protecting Guernsey’s S&P rating mattered.
He said protecting the credit rating was “not in any way the main driver of tax reform”, but one consequence of failing to address Guernsey’s structural deficit.

“The responsible question is not whether to invest but how to do so at the lowest possible cost,” he said.
He compared the approach to a family preparing to apply for a mortgage, saying a sensible household would put its finances “in the best possible shape” before approaching a bank because that helps secure the best rate.
Deputy Niles said the same principle applied to Guernsey, arguing that addressing the structural deficit would keep “the most affordable options open” for future investment.
He said a downgrade could increase borrowing costs, potentially adding around £750,000 a year in interest costs, or about £30m over a 40-year loan term.
He said that money would go “to lenders instead of into homes, infrastructure and public services”.
But why wasn’t S&P mentioned earlier?
That still leaves the thorny question of why P&R didn’t bring the S&P argument up earlier.
In February, Deputy Niles, then Economic Development Vice President, publicly highlighted S&P’s expectation that “a suite of tax reforms, including a Goods and Services Tax (GST)”, would be introduced from 2028.
So if Deputy Niles – and other members of P&R – were already aware of S&P’s importance months before the GST debate, why did the Tax Policy Letter not mention the ratings agency once?
More broadly, why had the issue not featured as a central public argument during half a decade of GST debate dating back to 2021?
Deputy Niles said the reason it was not specifically included in the policy letter was because protecting the credit rating wasn’t the “main driver of tax reform”, but rather one consequence of failing to address Guernsey’s structural deficit.
Questions also remain over whether civil servants modelled the effect on borrowing if the S&P rating dropped – and, if so, which deputies had seen that analysis.
Deputy Niles’s £750,000 estimate for the extra borrowing cost is based on a hypothetical 30 point increase in borrowing costs (0.3%).
However, he hasn’t clarified where that assumption comes from.
It is also unclear what evidence underpinned the illustrative 30 basis point increase in borrowing costs used during the debate, or whether that figure was based on modelling, market comparisons or another assumption.

There is also a separate question over whether S&P actually linked Guernsey’s rating to GST.
Deputy Rob Curgenven argued it did not, pointing out that GST is not mentioned in the report and that S&P instead referred to the need for “new tax-raising measures” to support a “large capital expenditure programme”.
He argued the warning was about maintaining a balance between spending and revenue, rather than requiring one specific tax measure.
Wider transparency row
The S&P argument was not the only issue where critics argued deputies had not been given the full picture before the vote.
Opponents have repeatedly raised concerns about access to information, including financial modelling, rejected Freedom of Information requests and the way key figures were presented during the debate.
Critics argue GST opponents were repeatedly challenged to produce detailed evidence for alternatives – whether controlling spending or alternative tax proposals – while P&R hasn’t held itself to the same evidentiary standards.
Whether or not deputies agree with that criticism, it goes to the heart of the transparency row.
If one side is expected to fully evidence its case, critics argue the same standard should apply to government.
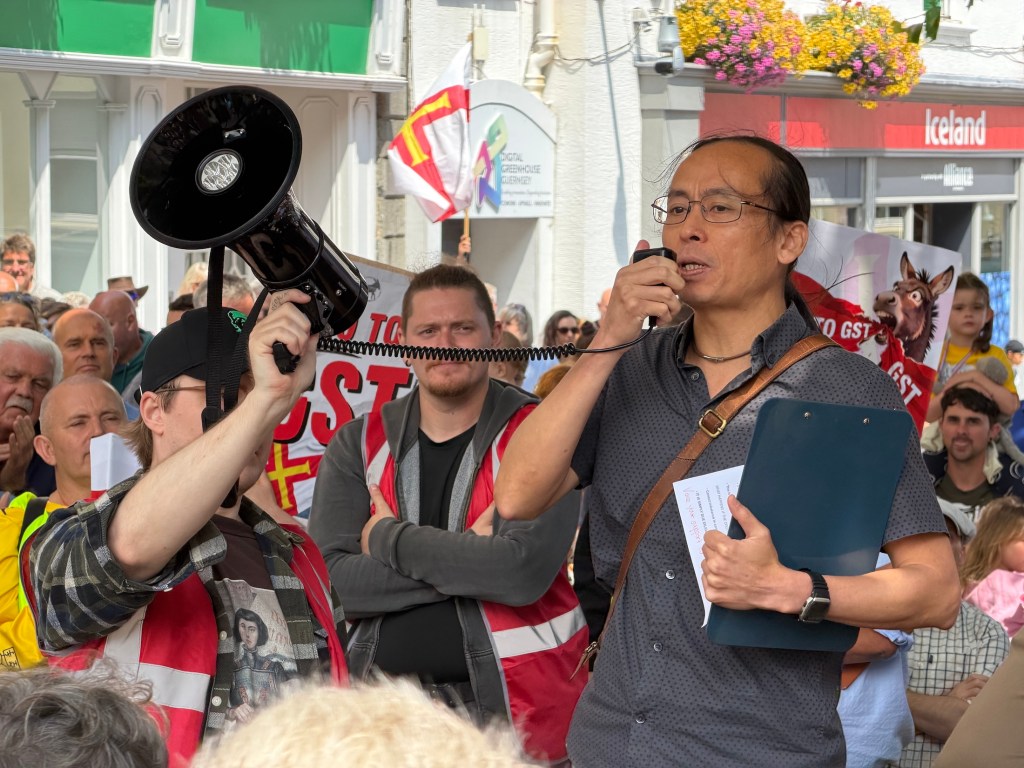
On top of this, there has been controversy over P&R’s £8k GST calculator and the ’emailgate’ revelation that at least one deputy bulk-deleted emails from voters – later recovering them after admitting it was a misjudgement.
But regardless of whether critics have been able to examine the evidence behind it, at least the “black hole” claim was made from the outset.
That is why the S&P row has widened the dispute about transparency – whether the full case for GST was presented at the start, or whether parts of the argument only emerged during the final debate.
Deputy Niles has argued that the S&P rating was “not in any way the main driver of tax reform”, which is why it wasn’t raised earlier or included in the policy letter.
Critics argue deputies should not be faced with what lawyers might describe as a ‘trial by ambush’ – where arguments or evidence appear too late for proper scrutiny.
Is it unfair for P&R to ‘later rely on in court’ something it ‘did not mention’ before?
P&R may disagree, but GST critics will certainly argue it ‘harms their defence’.